You open your brokerage statement and see trades you never placed. The securities don't match your investment plan, the account balance has fallen, and the representative insists you must have approved everything by phone. You search “unauthorized trading FINRA” and find broad warnings, but not the distinction that matters most: a trade can lack a phone call and still be authorized, while a broker can violate FINRA rules even when the customer has a long-standing relationship with the representative.
The first job is classification. Was the account non-discretionary? Did the firm have written authority? Was the transaction a permitted margin liquidation, a standing instruction, a stop order, or an options exercise? Then comes proof, damages, and the right recovery forum. Treating every disputed trade identically is how investors lose time and sometimes lose the claim itself.
What Counts as Unauthorized Trading Under FINRA
Consider an elderly customer who never placed a trade, never approved a transaction, and never gave the representative discretion, yet receives statements showing repeated activity. The broker may have had account access, login credentials, and years of communication with the customer. None of that, by itself, establishes trading authority.
Under the foundational FINRA framework, a representative must obtain customer authorization before exercising discretion in a non-discretionary account. The historical NASD Rule 2510(b) framework, which remains relevant to many disciplinary matters, prohibited a registered representative from exercising discretion unless the customer provided written authorization and the firm accepted the account in writing as discretionary. FINRA Rule 2010 separately requires associated persons to observe high standards of commercial honor and just and equitable principles of trade. The rules work together, but they answer different questions. One addresses authority to trade. The other addresses professional conduct.
The authority question
A non-discretionary account requires customer approval for each transaction unless a valid instruction or other recognized authority applies. A discretionary account permits the representative to select the security, quantity, price, or timing without obtaining approval for every order, but the arrangement must be properly established and accepted by the firm.
The critical point is simple: an account relationship isn't a blank check. A customer who routinely discusses investments with a broker hasn't automatically granted discretion. Likewise, a customer who previously approved one security hasn't necessarily approved a later purchase, sale, or strategy.
Investors should review their account agreements and any paperwork concerning what a discretionary account means. Look for the exact scope of authority, not just a reference to “managed” or “advisor-assisted” services.
Practical rule: If the broker can't identify the instruction, agreement, recording, or other evidence that authorized the specific transaction, the firm has a serious proof problem.
FINRA treats unauthorized trading as a serious customer-protection violation. In one matter involving a single unauthorized purchase, the applicable guideline recommended a $5,000 to $75,000 fine and a suspension ranging from 10 business days to one year. The representative ultimately received a $5,000 fine and a two-month suspension. Those sanctions don't determine an investor's civil recovery, but they show why FINRA doesn't treat unauthorized trading as a harmless administrative mistake. FINRA's disciplinary decision explains the single-purchase sanctions.
The Mechanics of Broker Authority and Customer Approval
Broker authority has layers. A customer may authorize a specific trade, provide standing instructions for a defined transaction, or grant broader discretionary authority. Those are not interchangeable arrangements, and a firm shouldn't blur them after a dispute arises.
In a non-discretionary account, the representative generally needs the customer's approval before entering each order. The approval can be documented through a recorded telephone call, a written message, or another reliable record, but the evidence must connect the customer to the particular transaction. A general statement such as “manage my account” usually doesn't answer which securities, quantities, prices, or timing the customer approved.
A discretionary account is different. The customer gives prior written authorization for discretion, and the member firm must accept the discretionary arrangement in writing. The representative still must act within the authority granted. A broad authority document won't necessarily justify trades that conflict with express restrictions, stated objectives, or the account's agreed mandate.
What records actually matter
Start with the account file, not the broker's explanation. Request and preserve:
- Account-opening documents: These identify whether the account was designated discretionary, non-discretionary, margin, retirement, or another account type.
- Discretionary agreements: Check signatures, dates, firm acceptance, limitations, and whether the document covers the disputed account.
- Order records: Order tickets should identify the representative, order type, security, quantity, price, and whether the order was solicited or unsolicited.
- Communications: Preserve emails, texts, letters, and recorded calls. Don't rely on screenshots alone if the original platform records can be requested.
- Confirmations and statements: These establish when the trade appeared and how the firm described it.
- Standing instructions: Identify the transaction category, frequency, security, and conditions that supposedly authorized the order.
Oral approval can still be disputed. A recording may show that the customer discussed a company without approving a purchase, or approved a small transaction while the representative entered a larger order. The question isn't whether the customer and broker spoke. It is whether the conversation authorized the transaction that was entered.
For a clearer account-level review, compare your documents with the explanation of non-discretionary brokerage accounts. The strongest cases usually present a clean mismatch between the firm's claimed authority and the documents created before the trade.
The Exceptions Most Investors Never Hear About
A trade can occur without a new approval call and still be authorized. Margin liquidation is the clearest example. If a margin account falls below the firm's maintenance requirements, the broker may have authority to sell securities without first consulting the customer. That authority depends on the account agreement and applicable rules, not on whether the customer expected a courtesy call. The SEC's explanation of unauthorized transactions addresses this margin exception.
The dispute turns on the source and limits of the broker's authority. Identify the account type, then determine what event supposedly triggered the transaction. A maintenance call, equity deficiency, option expiration, or other contractual condition may permit action without fresh consent. The firm still must show that the agreement covered the account, that the condition existed, and that its records match the order it entered.
Standing instructions create a different issue. A customer may authorize systematic investments, regular rebalancing, dividend reinvestment, or a defined withdrawal. The instruction should specify the transaction, timing, security or asset category, and applicable limits. “Keep the account balanced” is not a blank check for every later trade described as rebalancing.
Stop orders can execute after the stated market condition occurs. Options can be exercised or assigned under their governing terms. Forced sales may satisfy margin or other applicable requirements. Review each transaction against the original instruction or triggering event. A standing instruction that covers one security, amount, or frequency does not automatically cover a different order.
The right question is not whether you approved the trade that day. It is whether the firm had authority under the agreement or instruction, and whether it followed the required process.
This distinction matters for retirees with concentrated positions and for customers using margin. Accusing a firm of unauthorized trading despite a valid liquidation provision can damage credibility. The stronger complaint identifies the alleged trigger and shows why it did not exist, or why the firm exceeded the authority it had. Obtain the agreement, account records, notices, and order history before making the accusation.
How FINRA Sanctions Escalate With Pattern and Harm
A single unauthorized trade can trigger discipline. Repeated conduct, vulnerable customers, concealment, and measurable losses make the case substantially more serious. FINRA examines both the authority problem and the surrounding conduct.
In one proceeding, an 87-year-old customer held a non-discretionary account, yet trades were placed without authorization. The transactions produced $1,380 in commissions and $1,494 in realized losses. FINRA treated the conduct as a serious violation of the representative's professional duty under Rule 2010, rather than a paperwork defect. The FINRA decision involving the elderly customer describes the finding.
A separate case involved a deceased customer's account. The representative made unauthorized trades and facilitated unauthorized withdrawals. The sanction was a six-month industry suspension and a $10,000 fine. The FINRA proceeding provides the account and sanction details FINRA considered the number of customers, the number and value of transactions, customer losses, bad faith, and concealment. The customer's death and the withdrawals intensified the authority problem.
Pattern and harm change the outcome
The same record also shows how sustained conduct can end a career. The representative completed 38 unauthorized transactions over roughly two months in 2012, received a bar from associating with any FINRA member, and was ordered to pay $70,040.03 in restitution plus prejudgment interest. The Burford decision records those consequences.
FINRA's March 2024 Sanction Guidelines identify several factors that drive escalation:
- Customer impact: How many customers were affected and whether any were vulnerable.
- Transaction scope: The number and dollar value of unauthorized trades.
- Financial harm: The amount of customer loss.
- Intent and concealment: Whether the representative acted in bad faith or hid the activity.
- Regulatory response: Whether the respondent tried to evade the investigation.
Those factors also shape a recovery claim. One disputed trade usually demands precise proof of authority, causation, and loss. A recurring pattern can support wider damages analysis, discovery into compensation, and an argument that the firm should have detected the activity sooner. The current FINRA Sanction Guidelines identify these unauthorized-transaction factors.
Proving Unauthorized Trading With Records and Written Complaints
A disputed trade turns on the record, not memory alone. Preserve the account-opening documents, discretionary agreements, emails, texts, recorded calls, order tickets, confirmations, statements, login records, device records, and available audit trails. These materials can show whether the customer approved the order, gave a standing instruction, or never granted authority.
Do not change passwords, move assets, or close the account before preserving evidence unless immediate security concerns require action. If account takeover or identity theft is possible, secure the account promptly and document what changed, when it changed, and who reported it.
Reconstruct the order history
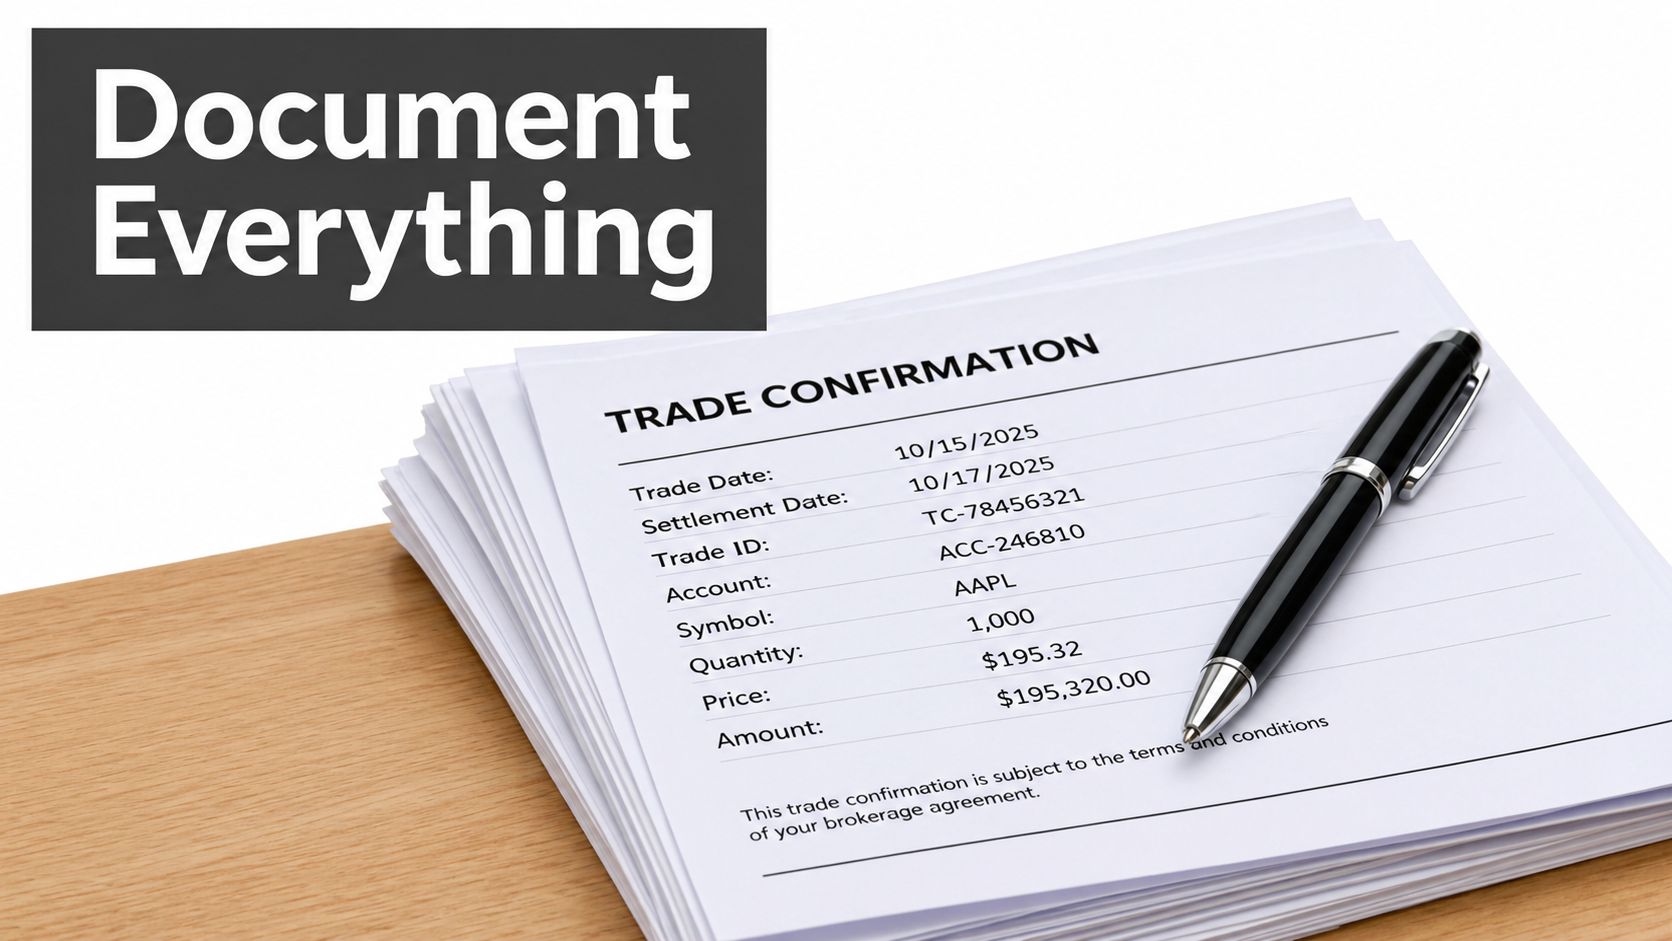
Build one row for every disputed transaction. Record the date and time, the representative who entered or supervised the order, the security and quantity, the price, and the order type. Mark whether the trade was a market order, limit order, stop order, option transaction, or liquidation.
Then identify the authority the firm relies on. It may point to a recorded call, written message, standing instruction, discretionary agreement, or margin event. Compare that explanation with the account's documented objectives, risk tolerance, cash position, margin status, and investment mandate.
This comparison often exposes the decisive inconsistency. A customer may have approved a sale while the representative entered a purchase. A nondiscretionary account may contain a ticket marked “unsolicited.” A firm may call a sale a forced margin liquidation even though the statements show no applicable maintenance deficiency. A standing instruction may authorize recurring activity without authorizing every unrelated trade.
Review what brokerage statements show against confirmations and the order-entry history. The timing matters. So do conflicting descriptions of the same transaction.
Put the complaint in writing. FINRA requires member firms to report certain written customer complaints within 30 calendar days when they allege theft, misappropriation of funds or securities, or forgery. The duty can apply even if the customer later withdraws the complaint. FINRA's Rule 4530 FAQ explains the reporting requirement.
Name the firm and representative, list each security and transaction date, describe the surrounding facts, and attach relevant records. State suspected theft, forgery, account compromise, or misappropriation accurately. Do not exaggerate. Keep delivery proof and every response. The written notice establishes what the firm knew and when it knew it, which can matter when the firm argues that the customer waited too long to object.
Measuring Damages in an Unauthorized Trading Case
A broker's unauthorized trade doesn't automatically equal the trade's entire face value as damages. The calculation must isolate what the trade caused, what the account would have held without it, and which costs flowed from the transaction.
Direct damages may include the decline in value of an unauthorized purchase, losses from an unauthorized liquidation, commissions, markups or markdowns, margin interest, taxes, and missed investment opportunities. The available measure depends on the facts, governing law, causation, and mitigation. A customer can't label every later account decline as unauthorized-trading damage without connecting the decline to the disputed order.
Build the counterfactual
A sound damages analysis starts at the moment before the trade:
- Establish the starting position. Identify the securities, cash, margin balance, and account value immediately before the disputed transaction.
- Calculate the actual result. Measure the purchase, sale, financing cost, commissions, markups, markdowns, subsequent liquidation, and realized or unrealized effect.
- Select a reasonable alternative. Determine what the position would have looked like if the trade had not occurred, subject to applicable causation and mitigation rules.
- Separate losses by cause. Distinguish market movement, fees, tax effects, concentration, margin costs, and harm caused by later transactions.
This model prevents two common errors. Some firms minimize the claim by pointing to the market generally, even when the unauthorized transaction created a concentrated position or unnecessary financing cost. Some claimants overreach by claiming every account loss without proving the link to the disputed orders.
The SEC Global Arena matter illustrates how transaction-level misconduct can become a firm-wide damages problem. The SEC alleged unauthorized trading in more than 360 retail accounts, more than $2.4 million in unlawful markups, markdowns, and commissions, and more than $4 million in net customer losses. The SEC litigation release describes the Global Arena allegations.
Look beyond the individual trade
Ask a forensic damages professional to examine compensation data, order volume, turnover, concentration, commissions, markups, markdowns, margin interest, and firm incentives together. A representative who repeatedly traded without authority may have generated compensation that helps explain motive and supports disgorgement-related theories. Internal blotters, portfolio systems, and original electronic audit trails can also matter, especially where later records were altered or incomplete.
The strongest model is transparent. It shows the position before the order, the actual outcome, the reasonable alternative, and the assumptions supporting each calculation.
Arbitration Versus Court Litigation for Recovery
A brokerage customer may discover unauthorized trades after the account statement arrives, only to find an arbitration clause in the account agreement. That clause can determine whether the investor sues in court, whether the firm can compel arbitration, and which claims remain available. Read the contract before choosing a forum.
FINRA arbitration is usually the practical route for an individual unauthorized-trading dispute. A securities-focused panel can address the orders, account records, and alleged losses. Discovery is generally more targeted than in federal litigation, and an award may include compensatory damages, interest where permitted, fees in appropriate circumstances, and other relief supported by the claim and governing rules.
Federal court provides a different set of tools. Discovery may be broader, legal motions more extensive, and appellate review available for certain legal errors. Court litigation may fit when arbitration is not required, when multiple investors have related claims, or when a court can grant relief an arbitration panel cannot. It also brings greater demands for time, expense, and procedural management.
Compare the practical tradeoffs
| Issue | FINRA arbitration | Federal court |
|---|---|---|
| Forum | Usually controlled by the brokerage agreement and FINRA eligibility rules | Depends on jurisdiction, contract, and applicable law |
| Discovery | More targeted and limited | Generally broader, subject to court rules |
| Decision-makers | Arbitrators with securities or legal experience, depending on panel selection | Judge and, where applicable, jury |
| Review | Judicial review is narrow | Appellate review may address legal errors |
| Individual claims | Often the practical path for brokerage disputes | May be available if arbitration doesn't control |
| Costs and pace | Often more focused, but fees and case costs still apply | More procedural steps can increase expense and duration |
Investors should understand the steps in FINRA arbitration before filing. Pleadings, evidence, settlement discussions, discovery requests, and hearing preparation follow a defined sequence, and mistakes early in the case can weaken the presentation.
A separate issue is pattern evidence. FINRA disciplinary analysis considers customer count, dollar losses, unauthorized-trade volume and value, and concealment or efforts to evade investigation. Those factors can help counsel determine whether the dispute appears isolated or supports broader discovery into repeated conduct.
Review the practical differences between arbitration and litigation early. A securities attorney should assess forum strategy before drafting the claim, not after the firm raises its arbitration clause.
A Practical Roadmap for Investors Who Suspect Unauthorized Trading
Act in sequence.
- Preserve the file. Save account-opening forms, statements, confirmations, order records, emails, texts, recorded calls, and login or device evidence before changing access where possible.
- Send a written dispute. Identify every transaction by date, security, quantity, and the reason you didn't authorize it. If theft, forgery, or misappropriation may be involved, describe the concern accurately so the notice creates a clear record.
- Challenge the firm first. FINRA directs investors to dispute the transaction with the firm in writing and preserve the correspondence. A regulatory complaint doesn't guarantee reimbursement.
- Get a securities-law evaluation. A lawyer can test authorization, standing instructions, margin authority, customer ratification, damages, and the arbitration clause. Kons Law is one firm that evaluates investment-loss recovery claims involving unauthorized trading and related broker misconduct.
- Protect the filing deadline. The FINRA Code of Arbitration Procedure generally requires filing within six years of the act or occurrence, while state-law and SEC claims can have different or shorter limitations rules. A practical scam-response guide from Gini Help can also help organize urgent reporting when account compromise or fraud is suspected.
Don't wait for the firm to finish an internal review before checking deadlines. A written complaint, FINRA complaint, and arbitration claim serve different purposes, and one doesn't automatically replace another.
If you suspect unauthorized trading, Kons Law can evaluate the trade records, account authority, communications, and potential investment-loss recovery options through FINRA arbitration or litigation. Call Kons Law Firm at (860) 920-5181 for a free, no-obligation consultation, or visit Kons Law to discuss your claim.
