You're probably here because something in your account stopped making sense. The balance dropped harder than the market. A trade showed up that you never approved. A broker who used to answer every call suddenly sounds evasive, or stops calling back altogether. Sometimes the first sign isn't even a bad investment recommendation. It's a password reset you didn't request, a wire confirmation you never authorized, or a statement that no longer matches what you were told.
That's how broker dealer fraud often looks in real life. It rarely arrives with a label. It shows up as confusion, missing money, changed records, and explanations that don't hold together.
If you suspect fraud, your job right now is not to argue with the broker. Your job is to lock down the facts, preserve the records, and move quickly enough to protect your recovery rights.
What to Do When You Suspect Broker Dealer Fraud
The first forty-eight hours matter more than most investors realize. If you think a broker, advisor, or brokerage firm mishandled your account, start collecting evidence before you start asking questions.
Start with the record trail
Pull every monthly statement you can access through the brokerage's online portal. Download trade confirmations, account notices, tax forms, secure messages, and any alerts tied to password changes, wires, or address updates. Take screenshots of current account balances, positions, recent activity, and any portal pages that look different from what you remember.
Then build a simple timeline:
- List each suspicious event. Unauthorized trade, unexplained loss, missing funds, margin use, wire transfer, or product purchase you don't understand.
- Match it to a document. Statement page, confirmation, email, text, voicemail, or call log.
- Write down who handled the account. Identify the specific registered representative assigned to you, not just the branch office.
Practical rule: Don't trust memory when money is missing. Preserve the document that proves what happened.
Don't call the broker first
Most investors do exactly that, and it's often a mistake. Once a broker or firm realizes a customer is connecting the dots, the story can harden fast. Notes get framed in self-serving language. Internal communications become harder to pin down. You want the records before you give anyone a chance to explain them away.
Request your complete transaction history and account records in writing. Ask for all documents tied to the account, including forms, approvals, authorizations, and communications. If you're comparing recovery systems in different jurisdictions, it can also help to see how Brosettlement works in UK, because procedure often shapes the situation as much as the facts do.
After the records are secured, speak with a securities attorney. That sequence matters. Evidence first. Strategy second.
Understanding What Broker Dealer Fraud Really Means
Broker dealer fraud isn't limited to a broker stealing cash or running a Ponzi scheme. It includes intentional misconduct by a brokerage firm or registered representative that misleads the customer, hides material facts, or puts the broker's interests ahead of the investor's interests.
A simple analogy works. You hire a pilot to fly you safely to your destination. Fraud happens when the pilot knows about a problem, hides it, takes a risk to benefit himself, and leaves you to absorb the damage. Investors do the same thing with brokerage accounts. They hand over trust, access, and often decision-making influence. When that trust is exploited through deception or self-dealing, you're in broker dealer fraud territory.
The duties that matter
You don't need to memorize rulebooks, but you do need to know the benchmarks. In practice, I look at a few core duties first:
- Suitability and investor profile. A broker can't recommend products blindly. The recommendation has to fit the customer's objectives, risk tolerance, liquidity needs, and overall situation.
- Best execution. Brokers have a duty to seek favorable execution for customer orders, not route trades in a way that serves the firm.
- Conflict disclosure. If the broker gets paid more to sell one product over another, that matters.
- Supervision. Firms are supposed to supervise their brokers and catch obvious misconduct before the customer gets wiped out.
- Accurate reporting and asset protection. Statements, confirmations, and account controls aren't paperwork formalities. They're part of safeguarding the customer's money.
If you need a plain-English overview of the broader category, this explanation of what investment fraud is is a useful starting point.
Misconduct is not rare
This isn't a fringe problem. A Stanford Law Review study reported that 4.63% of FINRA brokers had serious misconduct on their records and 7.35% had some misconduct history, and the same study reported that FINRA barred 246 individuals, suspended 375, and referred 970 fraud or insider-trading cases to criminal authorities in that year (Stanford Law Review study).
That matters because many investor losses don't come from one bizarre event. They come from patterns. Repeated unsuitable sales. Repeated unauthorized trades. Repeated failures by the firm to supervise a broker who was already showing warning signs.
Common Fraud Schemes and Red Flags to Recognize
Most investor claims fall into a handful of recognizable patterns. The labels differ. The mechanics don't.
Match the scheme to the red flag
| Fraud Scheme | How It Works | Key Red Flag |
|---|---|---|
| Unauthorized trading | The broker places trades without actual customer approval or without proper written discretionary authority | You see confirmations for trades you never discussed or approved |
| Churning | The broker overtrades the account to generate commissions or fees | Heavy trading with no clear investment purpose and rising costs |
| Unsuitable recommendations | The broker sells products that don't fit the investor's age, goals, liquidity needs, or risk tolerance | Your conservative account is suddenly loaded with risky or illiquid products |
| Misrepresentation in private placements or structured products | The broker downplays risk, lockups, fees, or concentration exposure | You were told the product was “safe” or “income-focused,” but the documents say otherwise |
| Ponzi-style or fixed-income impostor offerings | The investment is marketed as stable income, but money is diverted or recycled | Returns are described vaguely, and account records don't line up with what you were promised |
| Promissory-note sales through thinly supervised channels | The broker sells notes or private debt outside the normal account structure or with limited transparency | Payments, issuer details, or custody arrangements are hard to verify |
| Affinity fraud | The salesperson leverages religious, family, ethnic, or professional trust to bypass skepticism | The pitch relies more on shared identity than on verifiable disclosures |
What proves the pattern
The strongest fraud cases are document cases. You need to line up the sales story against the paper trail.
- Trade confirmations help prove timing, frequency, and whether activity was disclosed.
- New account forms and suitability questionnaires show what the broker knew about your objectives and risk tolerance.
- Prospectus delivery records and offering materials can expose omissions or contradictions.
- Emails, texts, and notes from meetings often show what was promised.
- Fee schedules and account agreements reveal whether the account structure itself created incentives to overtrade.
A bad outcome alone isn't enough. A mismatch between what you were told, what was documented, and what was done is where many strong claims begin.
For investors who want a broader checklist of deception patterns, this guide on how to identify investment scams is worth reading. A related concept appears outside the securities context too. This Law Office of Bryan Fagan PLLC guide on self-dealing is useful because it shows the same core problem: a person in a trusted role using that position for personal gain.
Churning has a legal test
Investors often say, “My broker traded too much.” That's not enough by itself. Churning is a specific fraud theory. The broker must control the account, the trading must be excessive in light of the customer's objectives, and the broker must act with scienter, meaning intent to defraud or reckless disregard of the customer's interests (Morgan Lewis churning overview).
That's why lawyers and arbitrators focus on account control, trade frequency, costs, and whether the activity made sense for the customer. High commissions are a clue. They are not the whole case.
Modern Digital Risks and Senior Investor Exploitation
A lot of broker dealer fraud coverage is stuck in the past. It talks about bad stock picks and ignores the modern entry point for losses: digital account compromise.
The fraud may start with your phone, not your broker
A criminal gets your login credentials through phishing. Or intercepts a verification process. Or impersonates firm personnel using a spoofed email, fake domain, or convincing voice message. Once inside, the fraudster changes contact details, requests a password reset, liquidates positions, or pushes out funds.
FINRA's oversight reporting for 2026 highlighted GenAI-enabled cyber fraud risks, including fake documents, phishing lures, and deepfake audio or video, alongside account takeover, spoofing, and credential-based attacks (InvestmentNews report on FINRA's 2026 regulatory agenda). The point isn't that every loss is the firm's fault. The point is that firms can't treat these events as random customer problems when red flags were visible.
Seniors are targeted differently
Older investors often get hit through emotional manipulation before the brokerage ever sees a transfer request. Romance scams, tech-support lies, and fake family emergencies are common pathways. The money may then move into or out of a brokerage account through wires, liquidations, or third-party transfers.
FINRA enforcement commentary also continues to emphasize senior-investor exploitation, Reg BI, private-placement due diligence, unauthorized trading, and supervision failures as active priorities (Morgan Lewis securities enforcement roundup).
If this risk touches a parent or spouse, read more about senior investment fraud.
Treat any unexpected request for a wire, password reset, or verification code as a stop sign. Call a known number you already have. Don't use the phone number in the suspicious message.
What firms should catch
Brokerage firms should scrutinize sudden changes in contact information, unusual transfer patterns, liquidations that don't fit the account history, and new third-party payees. When they miss obvious warning signs, the recovery case often becomes a supervision case as much as a theft case.
Legal Remedies Available to Injured Investors
Investors usually have three main paths after broker dealer fraud. FINRA arbitration, regulatory complaints, and court litigation. They do different jobs, and confusing them wastes time.
Comparing Recovery Forums for Broker Dealer Fraud
| Forum | Best For | Time Limit | Relief Available | Confidentiality |
|---|---|---|---|---|
| FINRA arbitration | Claims against FINRA-registered brokerage firms and brokers tied to customer accounts | FINRA generally bars claims submitted more than six years after the event giving rise to the claim (FINRA arbitration filing FAQ) | Monetary damages and other relief allowed under the claim and forum rules | More private than court, but not secret in the ordinary sense |
| SEC or state regulator complaint | Reporting ongoing misconduct, patterns affecting multiple investors, or conduct needing regulatory intervention | Timing depends on the agency process and doesn't replace your private filing deadlines | Regulatory investigation, sanctions, possible broader investor protection measures | Regulatory process, not a private damages forum for your personal case |
| Private civil lawsuit | Cases where arbitration is unavailable, claims extend beyond the brokerage relationship, or multiple non-FINRA defendants are involved | Depends on the legal claim and the applicable state or federal limitations period | Damages and, in some cases, additional forms of relief depending on the claims | Court filings are generally public |
What each route actually does
FINRA arbitration is usually the main recovery vehicle when your dispute is with the broker-dealer that held or serviced your account. Most customer agreements force these disputes into arbitration. That's not always bad. Arbitration can be efficient, and it's where many investor claims are decided.
A regulator complaint serves a different purpose. It can trigger scrutiny, pressure the firm, and help protect others, but it is not a substitute for filing your own case. Too many investors assume that if they report misconduct to a regulator, their money claim is somehow preserved. It isn't.
Court comes into play when arbitration clauses don't control, when defendants include outsiders to the brokerage relationship, or when the case involves wider fraud issues better suited to public discovery.
Timing is strategy
Timing isn't clerical. It shapes the case. If you wait too long, you may lose the arbitration forum entirely. FINRA's eligibility rule is one of the first dates I check because once the six-year window closes, that advantage can disappear fast.
Also keep this in mind: FINRA referred 1,369 fraud and insider-trading cases to the SEC and other federal or state law-enforcement agencies in 2024, and reported 1,759 market-abuse referrals in 2025, after 1,935 in 2023 (FINRA statistics). That level of referral activity shows why investor claims often involve conduct that regulators view as part of a broader market-integrity problem, not just a private customer dispute.
Evidence You Need Before Filing a Claim
You log in and see a transfer you did not approve. The phone number on the account has changed. Your broker says he never called you, but you have a voicemail that sounds exactly like him. That is not a paperwork problem. It is evidence, and if you do not lock it down fast, the firm will control the record before you do.
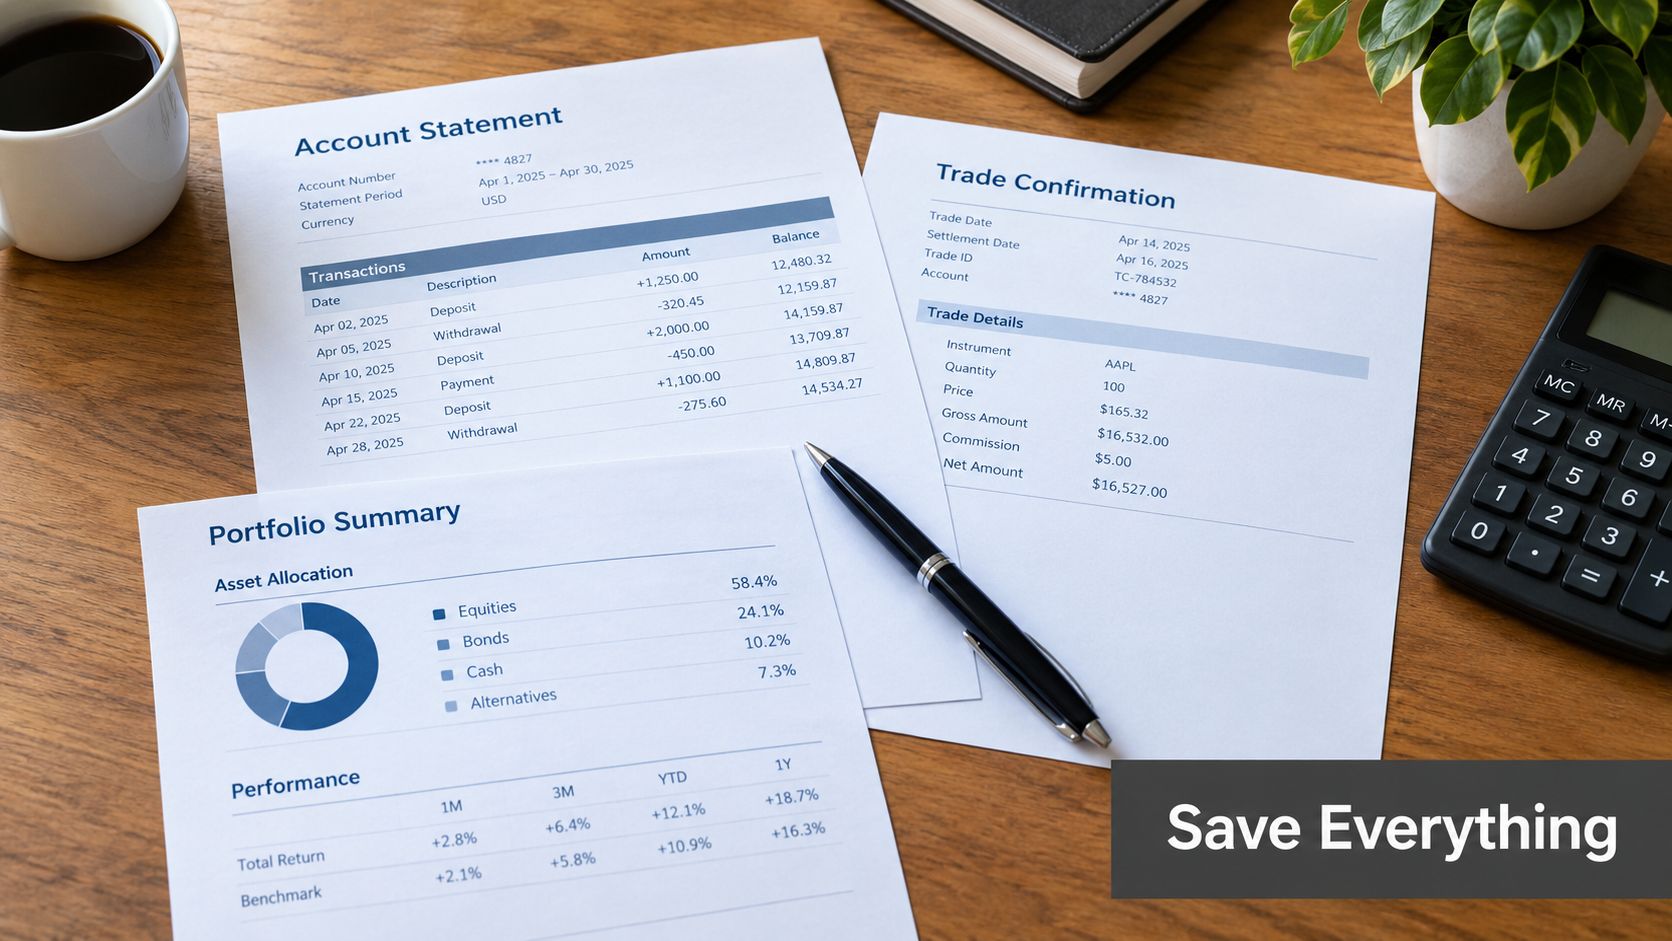
Start by building a timeline. Put every bad trade, transfer, recommendation, login alert, password reset, and conversation in date order. A clear chronology does two jobs. It shows whether this was classic sales-practice fraud, unauthorized trading, or a cyber-enabled account takeover. It also tells your lawyer which claims may still fit inside FINRA's six-year eligibility rule, which is often the first hard deadline that shapes case strategy.
Gather the records that define the account
Get the full paper trail, not just the latest statement.
- Monthly statements and trade confirmations. These show what was bought, sold, transferred, or margined, and when it happened.
- New account documents. Pull the account application, risk tolerance profile, investment objectives, trusted contact form, and any later updates.
- Account agreements. Include margin agreements, options approvals, advisory contracts, discretionary authority forms, fee schedules, and arbitration clauses.
- Notes of conversations. Your handwritten notes, calendar entries, and follow-up emails after calls can pin down what you were told and when you were told it.
Do not assume the account form helps the firm more than it helps you. In many cases, the opening documents expose the mismatch between what the investor asked for and what the broker sold.
Preserve the digital trail before it disappears
This matters even more in modern fraud cases. Account takeovers, spoofed emails, cloned voices, and fake advisor instructions leave electronic fingerprints, but those records can be overwritten, deleted, or scattered across devices and vendors.
Save and export:
- Portal screenshots that show balances, transaction history, changed contact information, linked bank accounts, secure messages, and login alerts.
- Text messages, emails, and voicemails from the broker, branch staff, or anyone claiming to be fraud prevention.
- Bank and wire records showing where money went, how it moved, and whether a new destination account was added.
- Access evidence such as password reset emails, multifactor authentication prompts, device-recognition alerts, and notices of profile changes.
- Audio or video impersonation evidence if you suspect a deepfake or spoofed call. Save the file, the caller ID screenshot, and the exact time of the contact.
If a senior investor was targeted, preserve evidence of who was involved in the communications and who benefited from the transactions. That often exposes pressure tactics, isolation, or misuse of a trusted contact role.
Send a preservation demand early
Do this in writing. Tell the brokerage firm to preserve account records, internal notes, call recordings, email and text communications, supervisory reviews, identity-verification records, IP logs, device data, and any fraud-monitoring or surveillance materials tied to the account.
Be specific. A vague complaint invites a narrow document hold. A targeted preservation letter gives you a better chance of preventing the routine loss of the exact evidence that proves unauthorized access or supervisory failure.
If identity theft or an account takeover is involved, file a police report and keep the report number. Then report the incident through the brokerage firm's fraud channel and keep copies of everything you submit.
Do not sabotage your own case
Investors do this all the time.
Do not delete messages. Do not reset devices until the relevant data is saved. Do not post about the dispute online. Do not rewrite your history to make it sound cleaner than it was. The ugly facts are usually manageable. Missing evidence is harder to fix.
A short text thread saved the day in more than one case I have handled. So has a login alert that proved the client was asleep in Florida while the account was accessed from another state.
Organize the file for the case you are actually going to bring
Your lawyer does not need a shoebox full of paper. Your lawyer needs a usable record. Sort the material by category and date. Flag the first bad recommendation, the first unauthorized trade, the first suspicious login, and the date you discovered the problem.
That organization affects more than convenience. It can shape how the claim is pleaded, who gets named, whether the dispute belongs in FINRA arbitration or court against additional parties, and how to approach arbitrator selection once the case is filed. Strong evidence also improves your position when the firm tries to blame the investor, claim approval was given, or argue the key events fall outside the eligible time period.
Kons Law handles FINRA arbitration and court actions involving broker misconduct, unauthorized trading, alternative investments, and related investor-loss claims.
How a FINRA Arbitration or Lawsuit Actually Works
Most investors have never seen a securities case before, so the process feels opaque. It's not mysterious once you break it down.
The arbitration track
You file a statement of claim through FINRA's dispute system. The brokerage firm answers. Then the case moves into arbitrator selection, scheduling, and document exchange.
The size of the claim changes the panel structure. Claims of $50,000 or less are handled as simplified arbitrations by one arbitrator. Claims between $50,000 and $100,000 use one arbitrator unless both parties agree in writing to three. Claims over $100,000, or requests for unspecified or non-monetary damages, default to three arbitrators unless both sides agree to one (SEC Investor Bulletin on broker-dealer/customer arbitration).
If you want a basic orientation before speaking with counsel, this overview of the FINRA arbitration process is helpful.
The substance of the case
Discovery in arbitration is narrower than court discovery, but it still matters. You exchange account records, communications, supervisory materials, and product documents. Witnesses may testify at the hearing. The investor's story has to be backed by paper, chronology, and credible damage analysis.
FINRA and SEC materials also treat churning as a technical fraud claim requiring proof of control, excessive trading, and scienter, with turnover, cost-to-equity, and similar trade-intensity metrics often serving as central evidence (FINRA OHO decision discussing churning standards).
When court is different
Court litigation is more formal and public. It may allow broader discovery and can be useful where multiple defendants are involved or where the dispute reaches beyond the account agreement. But many investors never get that choice because the customer agreement requires arbitration, and arbitration awards are generally binding.
Key Takeaways and Your Next Steps
You log in and see trades you did not approve, a transfer you did not request, or a voice message from your "advisor" that does not sound quite right. That is the moment to act like a claimant, not a customer waiting for an explanation.
Start preserving evidence immediately. Download statements, confirms, emails, text messages, call logs, portal alerts, wire records, and screenshots of anything that looks off. If you suspect an account takeover, deepfake impersonation, or other cyber-enabled fraud, report it to the firm at once in writing and keep a copy of that notice.
Timing controls strategy. FINRA's six-year eligibility rule can shut out older claims, even when the misconduct only became clear later. Panel selection also matters more than investors expect. The size of the case, the number of arbitrators, and how your claims are framed can affect how the panel sees unauthorized trading, unsuitable recommendations, supervision failures, or digital access fraud from the first conference forward.
Do not spend months waiting for the broker to "fix it." That delay helps the firm, not you.
Get the account records together. Identify every person and entity involved, including the broker, the branch, the introducing firm, the clearing firm, and anyone who touched the account credentials or transfer instructions. Build a clean timeline with dates, transactions, calls, and losses. Then ask direct questions about deadlines, forum choice, available claims, and what documents are still missing.
If you want to discuss the investment loss recovery process in more detail, call Kons Law Firm at (860) 920-5181 for a free, no obligation consultation.
Kons Law represents investors in FINRA arbitration and securities litigation when brokers, brokerage firms, or related financial professionals cause losses through fraud, misconduct, or supervision failures. If your account shows unauthorized trades, suspicious transfers, unsuitable investments, or signs of digital takeover, review your options and protect your recovery rights.
