You trusted a broker, adviser, or investment promoter with money you worked years to save. Then the account statements stopped making sense. The balance fell despite repeated assurances, trades appeared that you didn't authorize, or a private investment that was supposed to generate reliable income became impossible to value or withdraw from.
That moment calls for more than an angry phone call. Investment fraud law gives you potential routes to recovery, but those routes depend on evidence, timing, the identity of the responsible parties, and the forum selected for the claim. Public enforcement headlines may sound encouraging, yet an SEC penalty doesn't automatically compensate every investor who suffered a loss.
Your first priority should be to preserve evidence and determine the facts of what occurred. Your second should be to protect the claim from a deadline that may expire before the full fraud becomes clear.
What Investment Fraud Law Actually Covers
A long-time broker can cause serious damage without stealing money directly. The broker may recommend investments that don't fit your age, income, objectives, or need for liquidity. The firm may permit repeated transactions that generate commissions while your account declines. An adviser may fail to disclose a conflict that would have changed your decision.
That conduct can fall within investment fraud law, a collection of federal and state rules governing deception, omissions, unsuitable recommendations, unauthorized activity, and failures of supervision connected to securities transactions. The practical question isn't whether you lost money. It's whether someone violated a legal duty and whether that violation caused a recoverable loss.
The main legal theories
Investors most often encounter Section 10(b) of the Securities Exchange Act and Rule 10b-5 in claims involving material misstatements, deceptive conduct, or important omissions tied to securities transactions. A claim may focus on what a broker, adviser, issuer, or other participant said, failed to say, or did to create a misleading picture of an investment.
The Securities Act of 1933, including Sections 17(a) and 12(a)(2), can become relevant when offering documents or sales communications contain misleading statements or omit material information. The exact elements depend on the provision and the facts. State blue sky laws may provide additional remedies for misrepresentations, unregistered offerings, or sales practices that violate state securities requirements.
The law can address deliberate deception and, in some circumstances, negligent failures to provide required information. That distinction matters because proving an intentional scheme is different from proving that a professional failed to investigate, disclose, supervise, or recommend reasonably.
Civil recovery is different from government enforcement
An SEC investigation or Department of Justice prosecution may punish misconduct, restrain future violations, or create a fund for harmed investors. It doesn't replace a private claim against a brokerage firm, adviser, issuer, or responsible individual. In fiscal year 2024, the SEC filed 583 enforcement actions, obtained $8.2 billion in financial remedies, distributed $345 million to harmed investors, and received a record 45,130 tips, complaints, and referrals, including more than 24,000 whistleblower tips, according to the SEC's fiscal year 2024 enforcement announcement.
Those figures show the scale of enforcement, not the value of your individual claim. A private action requires its own proof of reliance where applicable, causation, damages, responsibility, and timeliness. The plain-language overview of investment fraud can help you identify the category of misconduct, but a lawyer must assess whether the facts support a legal remedy.
Common Fraud Schemes Investors Face Today
Fraud rarely arrives with a label. It arrives as a familiar broker's recommendation, a private placement presentation, a group-chat alert, or an online platform that appears polished enough to pass a casual review.
The most useful way to evaluate the problem is to compare the sales pitch with the account records. A promoter may promise stable returns while the statements show unexplained fees. A broker may describe a product as conservative while the account carries concentrated, illiquid, or borrowed positions. A fake platform may display profits that can't be withdrawn because the dashboard was never connected to real trading activity.
Patterns that deserve immediate scrutiny
- High-pressure solicitations: An unsolicited offer demands immediate funding, promises extraordinary returns, or discourages independent review. The pressure itself isn't conclusive, but it becomes significant when combined with unverifiable performance claims.
- Ponzi arrangements: Early participants receive purported returns funded by newer investors rather than genuine profits. Later statements may show consistent gains even though the investor can't obtain independent account records or a reliable explanation of the underlying business. Learn the warning signs described in this overview of Ponzi schemes.
- Affinity fraud: The promoter uses a religious, cultural, professional, military, or community relationship to lower skepticism. A trusted introduction doesn't validate the investment, and group participation can make victims delay reporting.
- Private offerings and alternative assets: Oil and gas interests, private placements, non-traded REITs, structured products, and similar offerings may be presented through glossy materials that conceal conflicts, illiquidity, valuation problems, or operational weaknesses.
- Digital-asset scams: Fake exchanges, cloned investment platforms, fabricated dashboards, AI-generated voices, and overseas scam centers can make a traditional broker pitch look entirely different. The FBI's 2025 Internet Crime Report recorded nearly $21 billion in U.S. cybercrime losses, with cryptocurrency-related complaints exceeding $11 billion and investment scams representing more than $8.6 billion, 72% of which involved cryptocurrency, as summarized in this FinCEN digital-asset investment-scam analysis.
- Broker misconduct: Churning creates excessive transactions, unauthorized trading puts positions into an account without permission, and misrepresentation disguises risk, fees, liquidity limits, or the actual history of a product.
Senior investors face an additional concern. A broker who knows a client depends on portfolio income should understand that illiquid or highly concentrated recommendations can create harm even when the product itself isn't fictitious. Fraud can also involve account takeovers, forged instructions, unauthorized withdrawals, or a trusted person exploiting access to an older investor's finances.
| Fraud Scheme | Typical Red Flag | Primary Legal Claim |
|---|---|---|
| Ponzi scheme | Returns appear steady, but withdrawals require recruiting new investors or repeated delays | Fraud, breach of fiduciary duty, negligent supervision |
| Churning | Frequent trades generate commissions without a rational investment purpose | Excessive trading, breach of contract, negligence |
| Unauthorized trading | Transactions appear without the client's approval | Unauthorized trading, negligence, breach of contract |
| Misrepresented private offering | Sales materials omit conflicts, liquidity limits, or how proceeds will be used | Securities fraud, negligent misrepresentation, statutory claims |
| Crypto investment scam | A platform shows gains but demands added fees before withdrawals | Fraud, conversion, payment-related claims, and tracing theories |
| Affinity fraud | Community trust replaces independent verification | Fraud, aiding or participation theories, negligent supervision |
These categories often overlap. A single relationship may involve an unsuitable recommendation, misleading statements about risk, excessive trading, and a firm's failure to supervise the representative. Don't force the facts into one label before reviewing the documents.
The Duties Brokers and Advisers Owe You
An investor who discovers an unexpected loss should first identify the professional involved. An investment adviser generally operates under a fiduciary framework. A broker-dealer's obligations arise from suitability principles and Regulation Best Interest when making recommendations. That classification affects how counsel examines conflicts, monitoring, product selection, and the full client relationship.
The SEC describes an investment adviser's federal fiduciary duty as having two core components, a duty of care and a duty of loyalty, as explained in this overview of fiduciary duty. The duty of care includes acting in the client's best interest, seeking best execution where applicable, and monitoring the relationship over time. The duty of loyalty requires full and fair disclosure of material conflicts and bars the adviser from putting personal interests ahead of the client's, according to the SEC's fiduciary-duty statement.
Apply the duty to the actual recommendation
A declining investment does not, by itself, prove fraud. Markets fall. The recovery question is whether the professional's conduct caused or worsened the loss. Examine these points:
- Was the recommendation reasonable? The professional should have gathered enough information about your objectives, finances, risk tolerance, experience, liquidity needs, and time horizon to assess the product or strategy.
- Were material risks disclosed? An investment presented as income-producing may carry significant credit, interest-rate, valuation, or liquidity risk. Written disclosures do not automatically cure a misleading verbal pitch.
- Were conflicts explained? Commissions, revenue sharing, proprietary products, referral arrangements, outside business activities, and compensation incentives may have shaped the recommendation.
- Were trades authorized and executed faithfully? A signed account agreement does not authorize every transaction. Compare your instructions with the orders entered and the statements that followed.
- Did the firm supervise? A brokerage firm may bear responsibility for inadequate oversight, ignored red flags, weak branch controls, or failures to investigate a representative's outside activities.
A representative's personal misconduct does not end the inquiry. Request and preserve account statements, trade confirmations, emails, written recommendations, compliance records, branch reviews, customer complaints, and supervisory responses. Those records may show that the firm saw warning signs before the loss and failed to act. Counsel becomes necessary when the documents reveal conflicting accounts, unauthorized activity, undisclosed compensation, or a firm-wide supervision problem.
Practical rule: Measure the professional's conduct against what you knew, what the professional knew, and what the firm should have discovered.
FINRA Arbitration vs Court Process
Your account agreement may determine where an investment-fraud claim must be filed. FINRA Rule 12200 generally requires arbitration when a customer requests it or when a written arbitration agreement applies. FINRA also states that customer claims ordinarily face a six-year eligibility limit, measured from the occurrence or event giving rise to the claim, as explained in its customer arbitration FAQ.
Forum choice should be addressed at the start. Learn about the differences between arbitration and litigation before a filing deadline or procedural ruling limits your position. An arbitration clause may control the forum, but it does not automatically make arbitration the better recovery path.
| Dimension | FINRA Arbitration | Court Process |
|---|---|---|
| Who decides | Independent arbitrators issue a final, binding decision | A judge may decide legal issues, and a jury may decide factual issues when available |
| Discovery | Document exchange and witness identification are available, but discovery is generally more limited in scope | Formal discovery may include broader document requests, depositions, interrogatories, and subpoenas |
| Timing | FINRA reported an average closure time of 13.4 months for overall arbitration cases in 2025, according to its 2025 dispute-resolution statistics | Timing varies with jurisdiction, case complexity, motions, discovery disputes, and trial availability |
| Cost structure | Filing fees, hearing fees, and other case expenses apply. Counsel may use contingency, hourly, or hybrid arrangements | Filing costs, attorney fees, expert expenses, discovery costs, and trial-related expenses may accumulate |
| Privacy | Arbitration is generally private | Court filings and proceedings are generally public |
| Appeal | Review is limited, and vacating an award is difficult | Appeals are available under applicable procedural rules |
| Potential defendants | Best suited to parties bound by the arbitration agreement or otherwise subject to the forum | May include issuers, promoters, individuals, and other defendants who are not FINRA members or agreement signatories |
FINRA remains a significant forum for investor-loss disputes. Its 2025 report lists 2,597 arbitration filings, with customer cases representing 63% of the total. The same report states that 84% of customer arbitration cases closed through settlement or paid damages in 2024, while reporting the 2025 average closure time above. These figures describe the forum, not your likely result. Your recovery will depend on liability, proof of loss, available defendants, and the respondent's ability to pay.
What arbitration does well
FINRA describes arbitration as generally faster and less complex than court litigation. The process includes filing fees, hearing fees, document exchange, and witness identification, as outlined in FINRA's arbitration and mediation information. Arbitrators issue a final and binding decision, so the hearing must present the legal theory, timeline, documents, and damages evidence clearly the first time.
Arbitration often fits a claim against a brokerage firm when the key records are in the firm's possession. It can reduce public exposure and may avoid some of the delay associated with court motion practice. The trade-offs are limited appellate review, narrower discovery, and less control over subpoenas and extensive witness examination. Arbitrators may understand brokerage practices, but counsel still must prove each element of the claim.
Court litigation can be the stronger choice when the case includes an issuer, promoter, adviser, or other defendant outside the FINRA agreement. Court may provide broader subpoena power, formal motion practice, and a jury option where available. It can also cost more and take longer, especially when defendants contest jurisdiction, remove the case, or raise pleading defenses. A broader defendant list may improve recovery prospects, but it also increases factual and procedural disputes.
Settlement talks do not necessarily stop eligibility or limitations deadlines. Have counsel calculate both periods independently, preserve the filing option, and use negotiations as part of the litigation strategy rather than as a substitute for filing. The right forum is the one that preserves viable claims, reaches the responsible parties, and gives the evidence a fair path to a decision.
Statute of Limitations and Discovery Rules
A claim can be strong and still disappear if it isn't filed on time. The difficult cases usually involve losses that accumulated gradually, because the investor may discover the full scheme long after the first warning sign.
For private securities-fraud claims under Exchange Act Section 10(b) and Rule 10b-5, the limitations framework has two layers. The suit must be filed within two years after discovery of the facts constituting the violation and, in any event, within five years after the violation. The five-year period is an absolute repose bar, meaning later discovery generally can't revive a claim after that period, as described in the U.S. Supreme Court's discussion of the limitations framework.
Inquiry notice changes the analysis
Discovery doesn't necessarily mean the day you finally prove the fraud. Courts may examine when a reasonable investor should have investigated suspicious facts. That is the inquiry-notice problem. A sudden account rebalancing, unexplained margin use, confirmation statements that don't match your instructions, missing distributions, or repeated excuses for withdrawal delays may trigger a duty to investigate before you understand the entire scheme.
Create a dated chronology as soon as you see a problem:
- Record when each transaction occurred.
- Save the first statement, email, call note, or notice that raised concern.
- Identify when you asked for an explanation and what response you received.
- Mark when you learned the investment, account, or adviser wasn't what you were told.
- Preserve communications that may show concealment or delayed disclosure.
FINRA's separate eligibility rule matters too. Customer claims are ordinarily subject to a six-year limit measured from the event giving rise to the claim, although the application of that rule depends on the facts and the forum. State securities laws and common-law claims may use different periods, and some can be shorter. Don't assume that a settlement conversation, internal complaint, or regulatory report automatically tolls every deadline.
The deadline is not the date you feel certain. It may turn on the date a reasonable investor should have investigated, or on the older date when the challenged violation occurred.
Have counsel analyze each potential claim separately. A broker's later reassurance may support concealment arguments, but you shouldn't rely on that theory without a legal review of the documents and governing law.
What to Do After You Discover Investment Losses
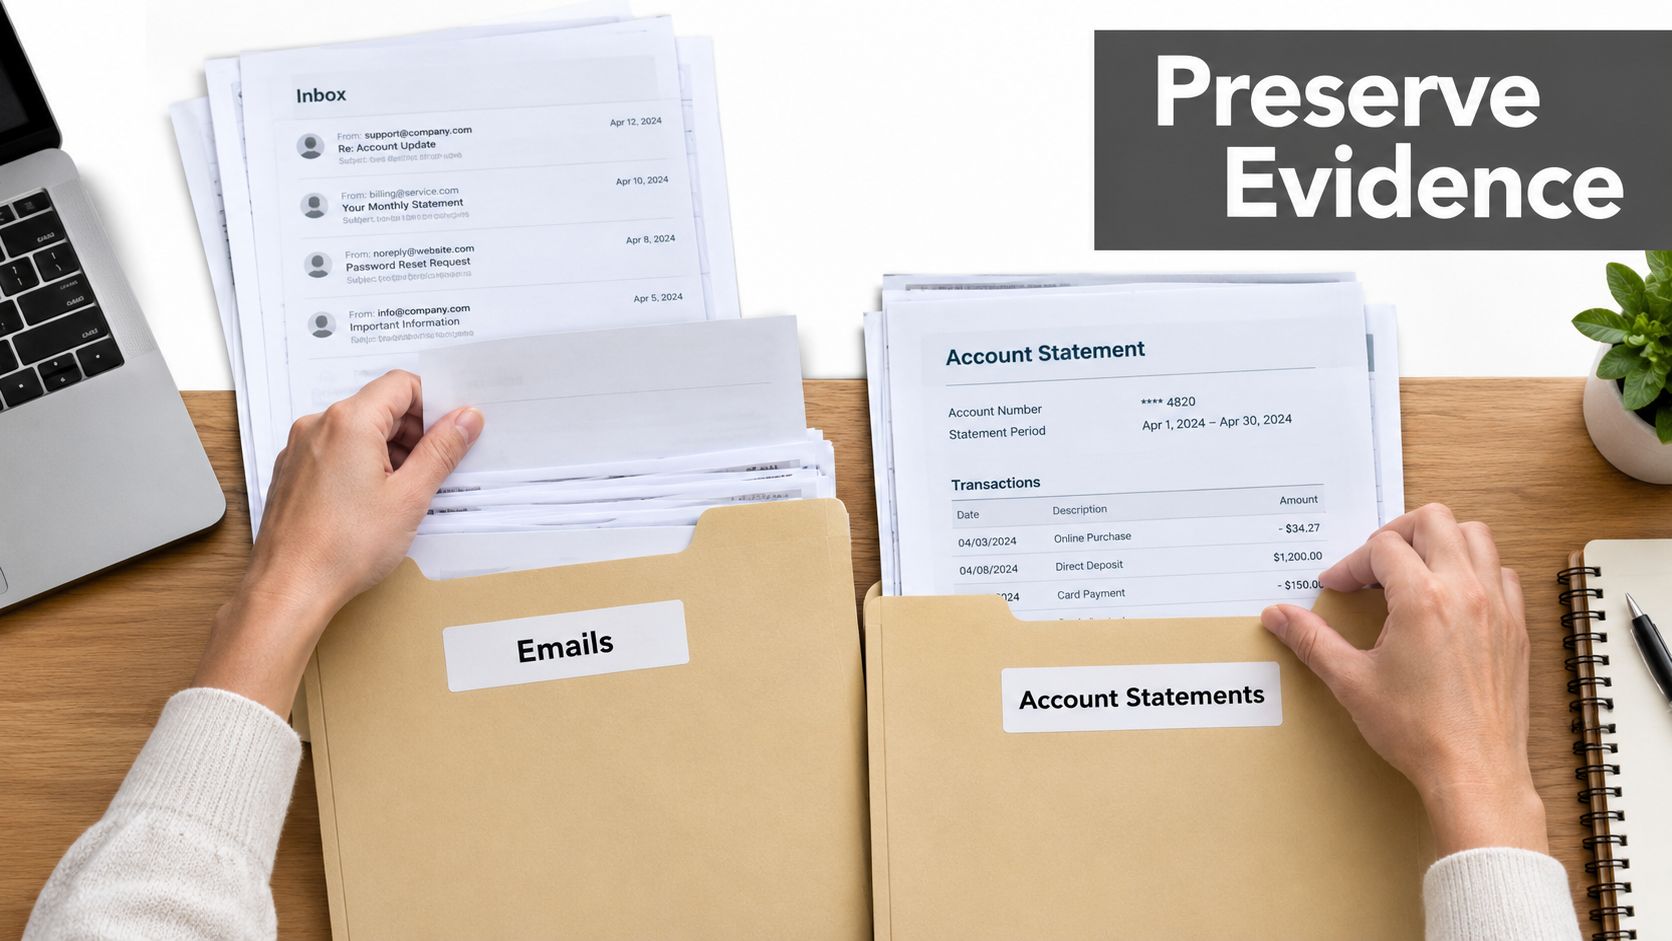
Start with preservation, not confrontation. If the broker or adviser is still explaining the loss, keep communications professional, but stop relying on that person to assemble the record. Request complete account statements, trade confirmations, transaction histories, account-opening documents, risk questionnaires, investment policy statements, prospectuses, private-placement memoranda, tax records, and communications.
Save the material outside the firm's portal. Download emails and attachments, preserve text messages, export account data where possible, and keep original files rather than only screenshots. Don't alter documents by adding notes to the originals. Create a separate working copy for annotations.
Build the loss timeline
Suppose your statement shows unfamiliar trades, an investment balance that never matches the promised value, and withdrawals that were repeatedly delayed. Write down the dates while your memory is fresh. Include every call, meeting, promise, explanation, transfer, complaint, and account change.
That timeline helps counsel evaluate discovery and inquiry notice. It also separates market loss from misconduct-related loss. A lawyer may need to compare the actual portfolio with a suitable alternative, identify commissions and fees, trace transferred funds, or determine whether the investment was ever purchased.
Choose counsel for the forum and facts
Look for experience with securities litigation, FINRA panels, broker supervision, and the specific product involved. Ask how the lawyer evaluates damages, which defendants may have assets or insurance, whether arbitration is required, and whether the proposed fee arrangement is contingency, hourly, or hybrid.
You can also consider reporting suspected misconduct to FINRA, the SEC, or a state securities regulator. A complaint may help regulators identify a broader pattern, but it isn't a substitute for protecting your private claim. Review the broker's public history through BrokerCheck and an adviser's disclosures through IAPD, then preserve what you find.
Don't post accusations on social media. Public statements can complicate negotiations, affect witness credibility, or create avoidable disputes about what you knew and when.
Key Decisions That Shape Your Recovery Path
Your recovery path turns on three questions: How strong is the evidence? What recovery is realistically available? How long can you wait?
Start with the documents. A signed statement, account record, email, recorded instruction, or private-placement document can be more valuable than a sincere recollection. Next, identify the loss theory. The claim might involve returned principal, excess commissions, unauthorized transactions, unsuitable concentration, lost opportunity, or funds diverted through a fraudulent platform. Each theory requires a different proof of causation and damages.
Then select the forum. FINRA arbitration may fit a dispute centered on a brokerage firm, while court litigation may be necessary when an issuer, promoter, payment intermediary, or other non-FINRA party is central to the loss. A related group of investors may share evidence and raise supervision or scheme-wide issues, but group proceedings also require careful coordination and an analysis of whether individual account facts differ.
Counsel should address settlement posture before filing, not after the defense has learned every weakness in your case. Early legal review can preserve claims, identify responsible parties, and prevent an investor from accepting a release that reaches claims that weren't understood at the time.
Don't wait for a regulator to finish investigating or for the promoter to admit the truth. If your records show unexplained activity, misleading statements, an unsuitable recommendation, or a failed withdrawal, have a securities lawyer evaluate the claim and the deadlines now.
Kons Law represents investors in securities and investment disputes through FINRA arbitration and court actions, including claims involving broker misconduct, unsuitable recommendations, unauthorized trading, private placements, Ponzi schemes, and other investment losses. If you want a candid review of your recovery options, visit Kons Law or call (860) 920-5181 for a FREE, NO OBLIGATION consultation about the investment loss recovery process.
