You mail a rent check, contractor payment, or investment distribution and assume the transaction is finished. Then the intended recipient calls because the check never arrived, while your bank statement shows it cleared to someone you don't know. By the time you investigate, the paper may have passed through several accounts and institutions.
That failure isn't theoretical. In the United States, check fraud has risen 385% since the COVID-19 pandemic, and Suspicious Activity Reports related to check fraud increased from over 350,000 in 2021 to more than 680,000 in 2022, according to the U.S. Treasury Department. The right response isn't panic or blind faith in a single banking product. It's a repeatable system that hardens the check, limits mail exposure, and gives your bank enough information to challenge suspicious payments quickly.
Why Check Fraud Is Back and What You Can Do About It
A retiree mails a $4,200 rent check from a suburban mailbox. Six days later, the landlord reports that it never arrived. The retiree checks the account and finds that the payment cleared to a different payee in another state.
That pattern is now familiar. Mail thieves target envelopes, alter checks after taking them, and exploit paper payments used for rent, contractors, gifts, and investment distributions. Check use has declined sharply, yet the remaining checks still attract criminals. Reducing paper payments helps, but it does not protect the checks you continue to mail.
Practical rule: Treat every mailed check as exposed property until the intended recipient confirms delivery and your account confirms the correct payment.
FinCEN identified 15,417 Bank Secrecy Act reports tied to mail-theft-related check fraud during a six-month review period in 2023, involving more than $688 million in suspicious transactions. Its analysis of mail-theft-related check fraud points to three controls: make checks harder to alter, reduce opportunities for interception, and review clearing activity quickly.
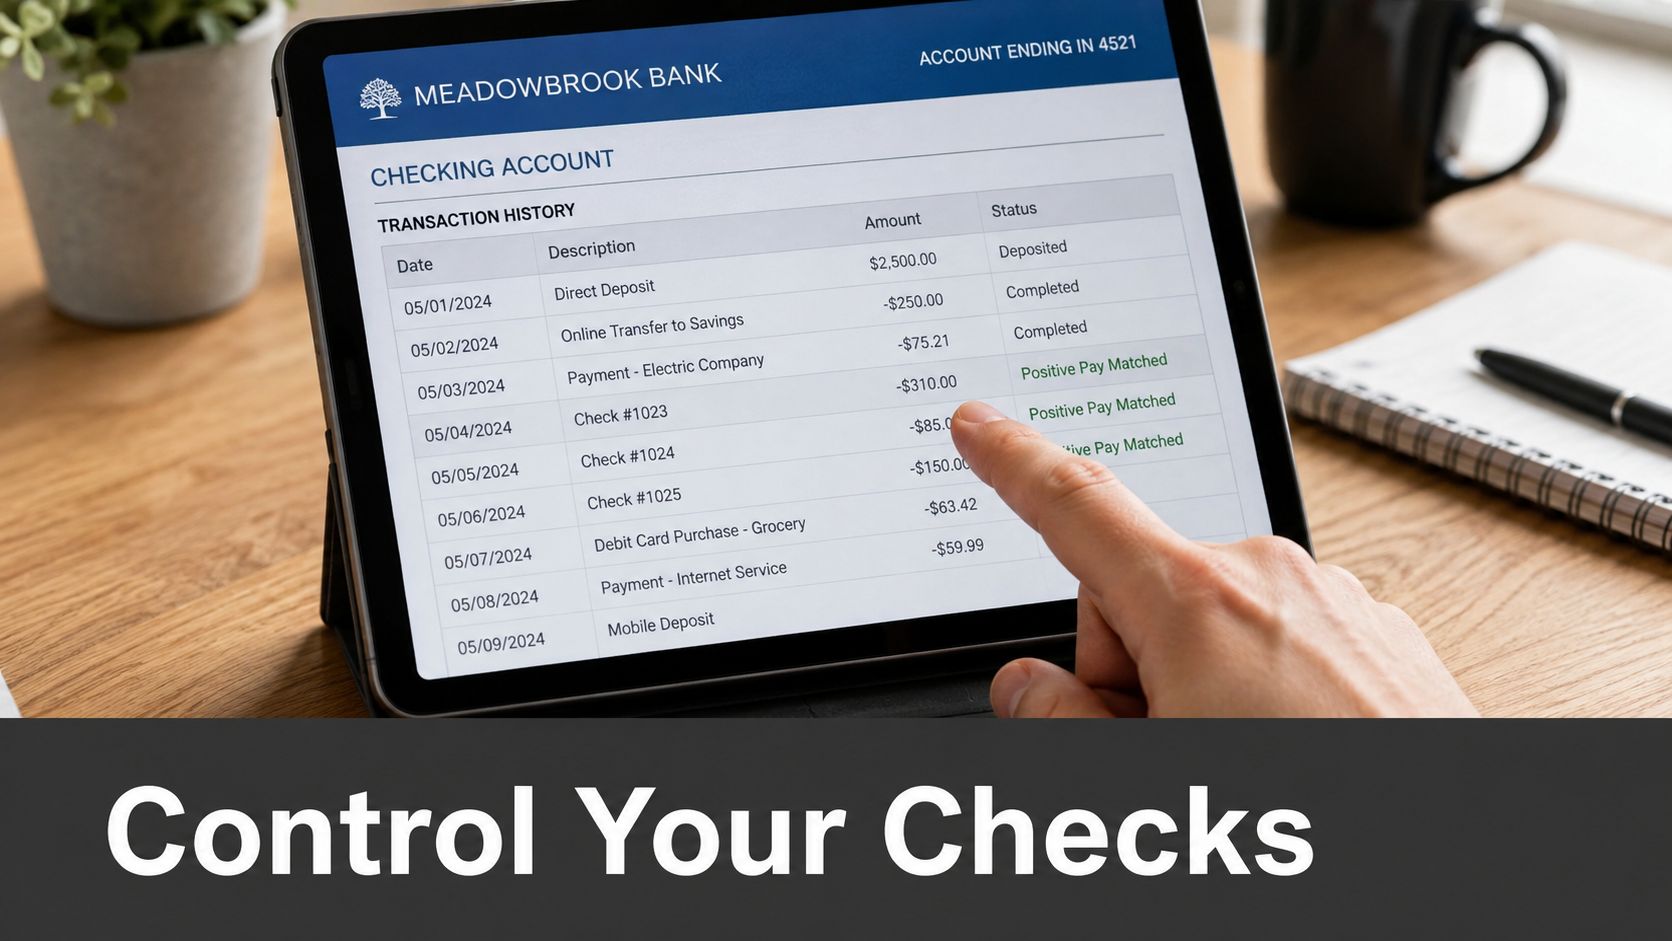
Your bank account needs controls as much as your envelope needs protection. Ask whether your bank offers Positive Pay or a comparable service that matches issued checks against presented payments. Businesses should connect those alerts with reconciliations, approval records, and fraud detection in small business bookkeeping. Personal account holders should review cleared checks and report discrepancies without delay.
Older adults and their families also need a plan for unusual payment requests, rushed instructions, and unexplained changes to payees. The risks described in this guide to financial elder abuse often overlap with check theft and account takeover.
Fraud after a check clears is not automatically a lost cause. Preserve the check image, contact the bank, dispute the unauthorized payment, and document every call and reference number. Prevention limits exposure, while prompt detection gives the bank a better chance to investigate and recover funds.
Writing Checks That Resist Theft and Alteration
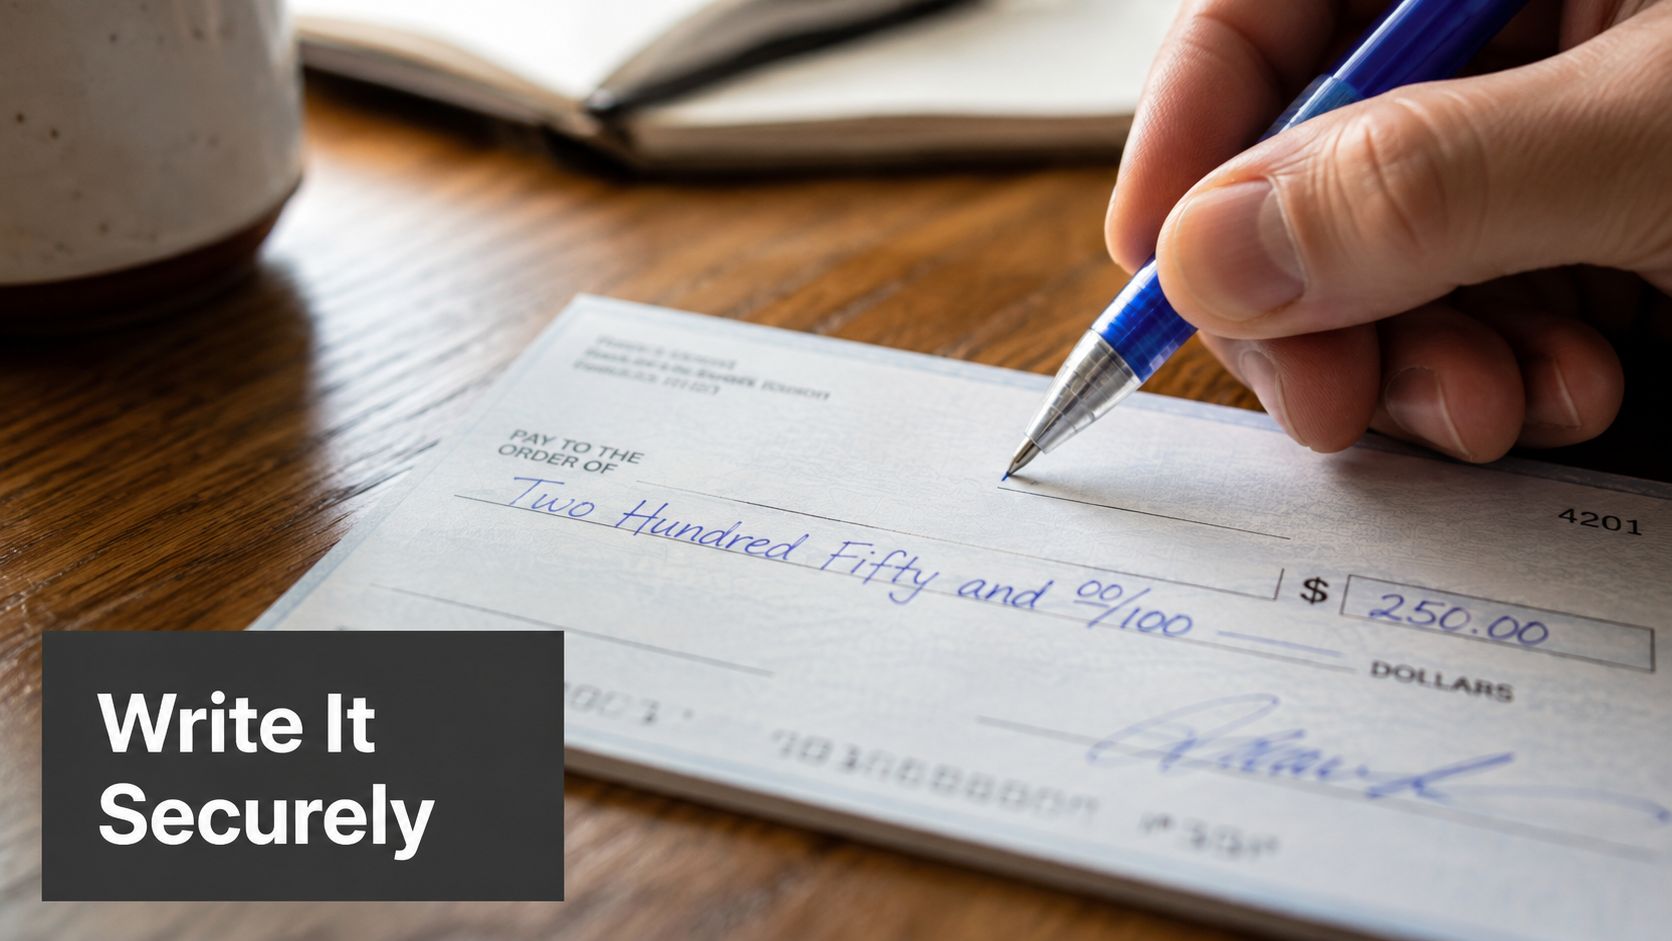
The check should give a thief as little usable material as possible. Use black gel ink or another permanent, nonerasable ink, never pencil or erasable ink. The OCC specifically recommends black gel ink because it resists check washing, and it advises writers to fill the amount in both words and figures clearly.
Write the payee's full name. On the amount line, start at the far left and draw a line through unused space. Do the same with the written amount. Don't leave room for someone to add words, numbers, or a second name. Your signature should remain in the signature area rather than crossing into the memo line or other blank fields.
Choose stock that shows tampering
Use checks with security features such as watermarks, patterned backgrounds, chemical-wash detection, or other tamper-evident printing. These features won't replace careful writing, but they make alteration more difficult and give a bank or recipient more visual clues.
Avoid printing unnecessary personal information. A check doesn't need your Social Security number, driver's license number, credit-card information, or other details that increase the consequences of theft. Businesses should also review whether full account numbers appear in visible address windows or on documents mailed with checks.
The OCC's check-writing guidance warns against blank spaces on the amount line and emphasizes clear amounts in words and figures. Those instructions remain practical because criminals exploit empty space and ambiguous handwriting, not just weak banking software.
Use this quick writing test
- Do: Use permanent black gel ink. Don't: Use pencil, erasable ink, or a light felt-tip pen.
- Do: Write the complete payee name. Don't: Use an abbreviation that makes substitution easier.
- Do: Fill unused lines and spaces. Don't: Leave open areas beside the payee or amount.
- Do: Review the check before sealing the envelope. Don't: Leave a pre-signed check or a blank signature line accessible.
- Do: Use security-featured stock. Don't: Assume ordinary paper provides meaningful protection.
For a broader explanation of the legal consequences when someone manipulates or uses a signature, see this discussion of whether forging a signature is illegal. The practical point is simpler: don't pre-sign checks, don't leave completed checks unattended, and don't put the payee and amount on the check long before you mail it.
Safe Mailing and Delivery Habits That Cut Exposure
A check left in an unsecured mailbox can disappear before you notice it. For an important payment, take the sealed envelope directly to a post-office counter or place it in an interior postal slot. If you use a USPS blue collection box, deposit it before the day's final pickup. Do not leave it overnight.
A locked residential mailbox reduces opportunistic theft, but prompt retrieval still matters. Collect delivered mail quickly, and never store outgoing checks in an unsecured home mailbox. If you cannot make a secure drop that day, hold the check until you can.
Match the delivery method to the payment
Registered, certified, and priority services offer different handling and tracking features. None makes a check immune to theft or alteration. For a high-value payment, confirm whether the service provides proof of mailing, delivery confirmation, insurance, or a signature requirement. Keep the receipt and tracking details with your payment records.
Mail theft deserves the same attention as check preparation. The same FinCEN analysis identifies substantial suspicious activity connected to stolen mail, and the Federal Trade Commission received 13,616 consumer complaints about fake check scams in 2024. Secure mailing reduces exposure, while prompt account monitoring and bank-side controls can help catch a fraudulent item before it becomes a settled loss.
Use electronic payment methods when they fit the relationship. ACH, a biller's payment portal, Zelle, or a wire can remove physical-mail exposure, but each method has separate verification and recovery rules. Checks remain practical for some investor distributions, certain contractors, family gifts, and recipients who cannot accept electronic payments. Confirm the recipient's payment details through a trusted channel before sending funds.
Treat your mailbox like a cash drawer. Handle it accordingly.
Bank and Account Controls That Catch Fraud Fast
Physical precautions reduce opportunity. Bank controls determine whether a suspicious check becomes a rejected exception or a settled loss.
Positive Pay is the central business control. The account holder sends the bank a list of authorized checks, generally including the check number, amount, and payee. When a check is presented, the bank compares it with that file. A counterfeit, altered, duplicate, or unissued check is flagged for review instead of passing through automatically. Some versions add image review and payee-name matching.
Positive Pay doesn't solve every problem. It can identify a check that was altered after issuance, but it may not detect an employee who was deceived into issuing a legitimate check to a fraudulent vendor. That is why the control must sit beside vendor verification, approval workflows, issued-check reconciliation, and dual approval for sensitive payments.
Federal Reserve reporting found that 32% of institutions saw increases in counterfeit checks, 21% saw more check washing, and 18% saw more payee forgery. Those figures are reported in the Federal Reserve article on check-fraud controls. The evidence points toward layered controls, not a single setting.
Who should ask for which control
- Small-business owners: Request Positive Pay, payee matching, daily exception review, and issued-check reconciliation.
- Landlords and trustees: Use alerts, payment logs, and dual approval when another person helps manage the account.
- High-net-worth individuals and investors: Ask whether a treasury account or enhanced checking product supports Positive Pay or a comparable service.
- Anyone with recurring payments: Turn on alerts for checks clearing, balance changes, new payees, and unusual activity.
Don't assume consumer accounts have no useful options. Banks may offer lighter services under names such as Check Positive Pay, transaction alerts, or account-monitoring tools. Ask your bank, in direct language, what check controls exist on this account and what it costs to activate them.
Businesses that manage payment counterparties may also benefit from organized identity and compliance help for sellers, particularly when a new vendor requests changed payment details. If suspicious activity moves beyond a single check, understanding suspicious activity reporting can help you communicate more effectively with the bank and investigators.
Monitoring and Detection Habits That Catch Problems Early
Reconcile the account weekly, not merely when a monthly statement arrives. A weekly review makes it easier to remember what you wrote, identify an unexpected payee, and contact the bank while records and recollections remain clear.
Use the bank's image archive. Compare the front of the cleared check with your records, then inspect the back for endorsement information that doesn't match the intended recipient. A check can be deposited without obvious changes to the front, so the endorsement deserves attention too.
Build a short fraud review
Keep a written or digital log with the check number, date, payee, and amount. During each review, look for:
- Unexpected amounts: A familiar check number appears for a different amount.
- Unknown payees: The name doesn't belong to a person or business you authorized.
- Sequence gaps: Check numbers appear out of order or a missing number clears unexpectedly.
- Duplicate presentments: The same check appears to have been submitted more than once.
- Unfamiliar endorsements: The back image shows a person or institution unrelated to the intended payee.
The Federal Reserve Financial Services survey reported that 63% of respondents experienced attempted or actual check fraud in 2024, making checks the payment method most often targeted in that survey. The Federal Reserve Financial Services survey data gives account holders a reason to treat monitoring as routine rather than optional.
Turn on text or app alerts for every check clearing and for balance changes. Set thresholds low enough to catch test transactions, because a small unauthorized payment may be reconnaissance for a larger attempt. Seniors and investors managing several accounts should schedule a monthly check-fraud review alongside bill paying. For help thinking through repeated or duplicate statement entries, Compass+ duplicate charge help offers a useful comparison point.
What to Do Immediately After a Check Is Stolen or Altered
Speed matters, but sequence matters too. Once you discover a stolen, altered, or forged check, create a written record and move through the following steps without waiting for the next statement.
- Call the issuing bank. Request a stop payment where possible, report the item as fraud, and ask for the bank's fraud-claim form. Ask what deadline applies to your account and obtain a confirmation number.
- Submit a written statement. Describe when you wrote or mailed the check, the intended payee, the amount, the check number, when you discovered the problem, and what the bank told you.
- Request both check images. Obtain the front and back images, including endorsement and deposit information. Preserve the envelope, receipt, tracking details, messages, and account statements.
- Report the theft. File with local police and obtain the case number. If the check moved through the mail, report it to the FTC and the U.S. Postal Inspection Service as well.
- Contact affected payees. Tell every intended recipient whose check number is missing, altered, or delayed. Confirm whether the payee received a different item or never received anything.
- Ask about further screening. Request an Account Number Check Verification or comparable bank service that can flag further attempts involving the compromised account.
A stolen check exposes more than the payment. It may reveal your account and routing numbers, which is why you should discuss closing the compromised account and moving legitimate automatic payments to a new one. Don't let convenience override containment.
The Federal Reserve has reported that financial institutions increasingly urge customers to avoid mailing checks and use electronic payments, while banks continue developing Positive Pay and other mitigation tools. If the incident involves investment proceeds, a brokerage account, an advisor, or a trustee, a securities attorney can help trace funds across institutions, pursue recovery from potentially negligent banks, and coordinate communications with law enforcement. Review the related guidance on unauthorized withdrawals when the loss extends beyond the check itself.
Recovery is not guaranteed, but a stolen check is not automatically a lost cause. Preserve evidence, notify the right parties promptly, and avoid accepting a bank's first explanation without reviewing the transaction record.
Turning Prevention Into a Repeatable Monthly Habit
A calendar beats good intentions. On the 1st, check your supply of security-featured checks and order more before you're forced to use an old or poorly protected batch. By the 5th, reconcile the prior month's account against paper or digital statements and flag unfamiliar payees or check images.
On the 15th, vary mailing days when practical, confirm that check-clearing and balance alerts remain active, and review any pending high-value payments. On the 28th, verify Positive Pay enrollment, exception-review settings, authorized users, and beneficiary lists.
The routine should take roughly twenty minutes per month. Seniors may benefit from assigning one trusted family member or fiduciary to participate, especially when several accounts or recurring distributions are involved. That person should review records with permission, not take informal control of funds.
Bring in a securities attorney when losses recur, beneficiary details change without authorization, or a check is altered or cashed despite your controls. Keep FTC ReportFraud, the U.S. Postal Inspection Service, and your bank's fraud department in your standing contact list.
If you need help evaluating losses tied to check fraud, unauthorized withdrawals, broker misconduct, or investment-related payment failures, Kons Law handles investor recovery matters through FINRA arbitration and court actions. If you would like a free consultation to discuss the investment loss recovery process in more detail, call Kons Law Firm at (860) 920-5181 for a FREE, NO OBLIGATION consultation.
